Appetite for ownership risk has also returned: equity rose to 83 per cent of inflows in H1 FY27, while structured debt halved to 16 per cent from 32 per cent in FY23.
FinTech BizNews Service
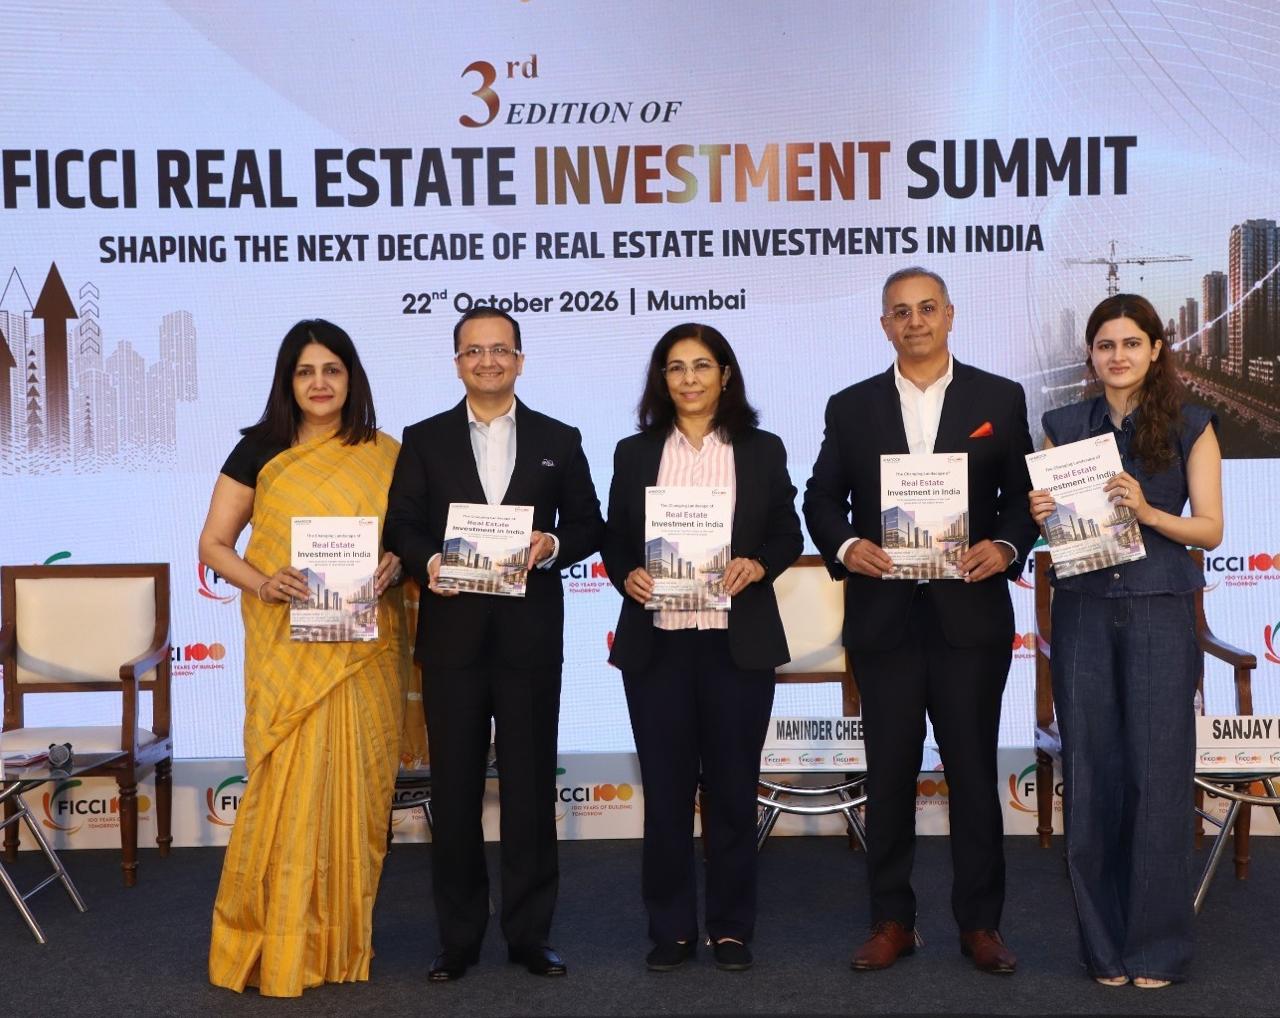
Mumbai, 21 October, 2026: Data centres have overtaken offices as the largest destination for private equity in Indian real estate. Domestic funds now supply more than two-fifths of that capital, according to The Changing Landscape of Real Estate Investment in India, a report released by FICCI and Anarock.
Private equity investment reached $6.1bn across 55 disclosed deals in the first nine months of 2026, close to the $6.9bn recorded for the whole of 2025. Data centres took $2.5bn, or 40 per cent, ahead of offices at $1.7bn. If this pace holds, 2026 would be the strongest year since 2007.
Private equity investment reached $6.1bn across 55 disclosed deals in the first nine months of 2026, close to the $6.9bn recorded for the whole of 2025. Data centres took $2.5bn, or 40 per cent, ahead of offices at $1.7bn. If this pace holds, 2026 would be the strongest year since 2007.
The shift in the source of capital is sharper still. Domestic funds invested $2.6bn over the nine months, up from $0.4bn in 2020. That 6.4-fold rise has lifted their share of private equity value from 8 per cent to 42 per cent. In the first half of FY27, they took 48 per cent of inflows, triple their share in FY25. Foreign capital has not retreated, growing about 19 per cent a year between 2021 and 2025 to $4.9bn. Appetite for ownership risk has also returned: equity rose to 83 per cent of inflows in H1 FY27, while structured debt halved to 16 per cent from 32 per cent in FY23.
The report shows operational data centre capacity growing about 30 per cent to 2,200 MW in 2026, and beyond 6.7 GW by 2030, with more than $300bn in commitments announced. Indian assets trade at $10mn to $15mn per MW, against $20mn to $30mn in the US and Singapore. The report identifies power availability, not land, as the binding constraint.
Capital is also spreading beyond the metros. The Mumbai Metropolitan Region took 49 per cent of private equity value between 2021 and 2025. Tier II cities hold only 3 to 4 per cent, but their deals rose from 11 in 2016-20 to 20 in 2021-25, across 12 cities rather than eight. Some 45 per cent of branded hotel keys signed in H1 2026 were in Tier 3 and 4 cities, and 1.4 to 1.6 GW of data centre capacity is planned outside the top six cities. Multi-city platforms, which took 49 per cent of inflows in H1 FY27, connect the two engines.
Demand is strong but uneven. Residential sales in the top seven cities reached a record Rs6.1 lakh crore in FY26, more than double FY22. Yet high-end and luxury homes rose to 45 per cent of new supply from 13 per cent, while the affordable share fell to 14 per cent from 25 per cent.
The financing task is large. The report finds that no single capital pool can fund the next ₹10 lakh crore of investment. At the 2021-25 pace, private equity would supply about $55bn over a decade. Early-stage money is scarcest, because RERA requires 70 per cent of buyer collections to sit in escrow. The report expects platform equity, structured private credit and lease-backed exits through REITs and SM REITs to fill the gap.
Mr Raj Menda, Chairman of the FICCI Committee on Urban Development and Real Estate and Chairman of the Supervisory Board at RMZ, said, “Real estate will be the physical platform for India’s growth: offices that compete with the best in the world, homes that are affordable and well located, warehouses and industrial parks that keep supply chains efficient, and data centres that power the digital economy. Deepening domestic capital markets, REITs, small and medium REITs and alternative investment funds, making it easier to build and taking growth beyond the largest metros are the three priorities for industry and government.”
The sector, valued at about $600bn in 2025, is projected to reach $1tn by 2030, when its share of GDP is expected to rise to 13 per cent from about 6 per cent in 2017. The report’s five calls for 2030-35 are deeper institutionalisation, continued consolidation, domestic capital as the second engine, alternatives moving into the core, and credit filling the early-stage gap.