Average Capacity Utilization Rise;
FinTech BizNews Service
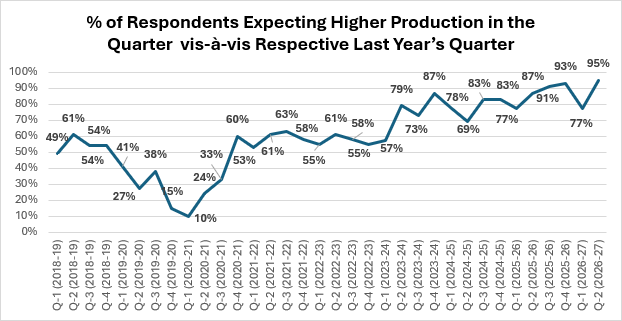
Mumbai, 06 October, 2026: The latest edition of the FICCI Manufacturing Survey reflects rebound in the sentiment for production in Q-2 2026-27 compared to the previous quarter indicating signs of recovery from the West Asian crisis. Responses were based on expectations of the manufacturers reflecting the overall positive sentiments and stable domestic fundamentals for manufacturing growth. In comparison to Q1 FY 2026-27, when 77% of respondents reported higher or same production levels, approximately 95% of respondents reported either higher or same production levels in Q2 FY 2026-27. This positive outlook was also evident in demand, as 90% of respondents reported higher or same orders in Q2 FY 2026 as compared to 77% in the previous quarter.
FICCI’s latest Quarterly Survey on Manufacturing (QSM), which is the 71st edition of the survey, assessed the performance and sentiments for Q2 July-September 2026-27 of manufacturers for nine major sectors namely, Automotive & Auto Components, Capital Goods, Chemicals and Allied Products, Electronics & Electricals, Glass, Machine Tools, Metal & Metal Products, Textiles, Apparels & Technical Textiles and Miscellaneous. Responses have been drawn from manufacturing units from both large and SME segments with a combined annual turnover of over Rs. 2 lac crores.
Capacity Addition & Utilization
There is a positive impact seen on the capacity utilization vis-à-vis the previous quarter. The existing average capacity utilization in manufacturing is close to 75%, which is higher than the capacity utilization of 72% in the previous survey. The future investment outlook is steady for the next six months. Challenges faced by respondents in expanding capacities include uncertainty due to current geopolitical situation (tariffs, trade restrictions, demand uncertainty), operational issues (skill/labour availability, raw material shortages, increasing logistic costs, regulatory challenges). The table below gives average capacity utilization for various sub-sectors of manufacturing:
Current Average Capacity Utilization levels as reported in survey (%)
Sector | Average capacity utilization (%) |
Automotive & Auto Components | 73 |
Capital Goods | 76 |
Chemicals and Allied Products | 71 |
Electronics & Electricals | 70 |
Glass | 88 |
Machine Tools | 68 |
Metal & Metal Products | 78 |
Miscellaneous | 81 |
Textiles, Apparels & Technical Textiles | 75 |
Average Total | 75.5 (approx.) |
Inventories
In Q2 2026-27, around 89% of the respondents reported higher or same level of inventory and for Q-1 2026-27, around 91% of the respondents reported higher or same level of inventory.
Exports
In exports, about 74% of respondents reported higher or same level of exports in Q1 FY 2026-27 and in Q2 2026-27 around 80% of the respondents reported their exports to be higher or same as compared to previous year’s similar quarters. Export diversification efforts by government and industry seem to be yielding results.
Hiring
43% of the respondents are looking at hiring an additional workforce in the next three months as compared to 35% in the last quarter.
Interest Rate
The average interest rate paid by the manufacturers has been reported to be 9.1%, as compared to 8.9% reported for the last quarter. 90% of respondents reported sufficient availability of funds from banks for working capital or long-term capital.
Sectoral Growth
Based on expectations, the likely sectoral growth range is shown below:
Growth Expectations for Q-2 FY 2026-27
Sector | Growth Expectation |
Capital Goods | Moderate |
Glass | Moderate |
Chemicals and Allied Products | Moderate |
Electronics & Electricals | Moderate |
Machine Tools | Strong to Moderate |
Metal & Metal Products | Strong to Moderate |
Textiles, Apparels & Technical Textiles | Moderate |
Automotive & Auto Components | Strong |
Miscellaneous | Moderate to Low |
* Very Strong >20%; Strong 10-20%; Moderate 5-10%; Low < 5%;
Source: FICCI Survey
Production Cost
Production costs for manufacturers in this quarter seem to remain on higher side. Nearly 83% of respondents reported an increase in the cost of production as a percentage of sales, as against 79% in the previous quarter, indicating that costs pressures were higher in this quarter. The increase in cost of production compared to last year is mainly due to higher raw material costs, energy costs, currency depreciation, and increased logistics, and utility costs.
Workforce Availability
Most sectors are not facing shortage of labor at factories as around 67% of respondents mentioned that they do not have any issues with workforce availability. The remaining 33% feel that there is still lack of skilled workforce available in their sector and there is a need to step up efforts both at government and Industry level.